Know Your Options Before Anyone Asks You to Decide
Education comes first. Learn how to turn what you've saved into retirement income, protect your family and pass on what you've built. Thurman Financial explains your options in plain language.
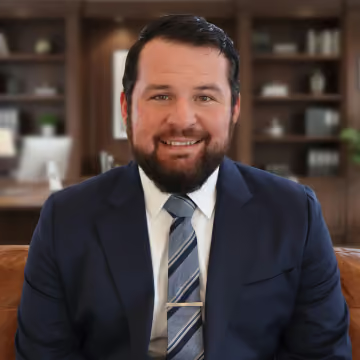
Austyn Thurman
- Founder, Retirement Advisor
Austyn Thurman is a retirement advisor in Columbus, Ohio, who puts education first, and a former sales trainer who coached 60 to 90 people a year at a large, well‑known corporation.
I'm here to give you the information. You want to work with me? Great. If you don't, I still want you to know what's out there. At the end of the day, it's got to be your decision. I do more of a pull, not a push. I'm here to help you make the right decision for your family, and sometimes that's not me.
Where Retirement Decisions Go Wrong
It isn't always one bad product. Sometimes it's deciding without the full picture.
Deciding Before You've Been Heard
It's easy to be handed an answer before anyone has asked you a question. Annuities are the way. Insurance is the way. Stocks are the way. If nobody asked what you want your money to do, you can't tell whether what you were offered fits you. A good first conversation starts with your family and your plans, and it's fine if it ends with no change at all.
See how this works: Deciding Before You've Been Heard
Owning Something You'd Like Explained
You may own a policy or annuity without knowing what it charges, how long your money is tied up, or which parts are guaranteed. Those answers are in the contract, and it's better to find them before something forces the question. Austyn Thurman will go through it with you in plain language.
See how this works: Owning Something You'd Like Explained
No Plan for Who Comes Next
A plan that stops at you leaves your family guessing. Beneficiaries go out of date, accounts pass under different rules, and the person who set it all up may be retired by the time your family needs help. Thinking about this now gives your family clear instructions and someone to call.
See how this works: No Plan for Who Comes NextHow We Help You
Retirement income, annuities and life insurance, explained in plain language before you decide anything.
Where Your Monthly Income Comes From
Once the paychecks stop, every month's income has to come from somewhere. Austyn Thurman goes through where yours comes from, how long it can last and what's guaranteed.
Annuities and Guaranteed Lifetime Income
Fixed and fixed index annuities can pay income for life, under the terms of the contract. You'll see what that costs, how long your money is tied up and when an annuity isn't the right answer. Guarantees depend on the issuing insurance company's claims‑paying ability.
401(k) and IRA Rollovers
Left a 401(k) at an old job? Moving it into an annuity is one option, and it isn't always the right one. You'll see what you'd get, what you'd give up and when to leave it where it is.
Pension Maximization
Taking the higher pension payment and buying life insurance for your spouse can work, and it can also go wrong. That choice is often permanent, so Austyn Thurman goes through it with you before you make it.
Term, Whole and Final Expense
Start with what the money is for. Replacing your income while your kids are growing up is a different job from covering final costs, and the right policy depends on the job.
Universal and Indexed Universal Life
An indexed universal life (IUL) policy is permanent coverage with a cash value that can earn interest based partly on a market index. It also has charges and limits, and it can lapse if it runs short. Austyn Thurman cares a lot about this one and will show you all of it before you decide.
Coverage for Business Owners
Key person coverage, buy‑sell funding and executive bonus plans use life insurance to plan for the people a business depends on. Your attorney and CPA should weigh in on how yours is set up.
Legacy and Wealth Transfer
A good plan covers your whole family for years to come. That means current beneficiaries, life insurance that reaches the right people, charitable giving if it matters to you, and a family that knows who to call.
Estate Planning With an Attorney
Wills and trusts need an attorney, and Austyn Thurman works with one when you need it. Our part is the insurance side, such as your policies and beneficiaries.
Policy Reviews and Second Opinions
Already own a life insurance policy or fixed annuity and want to know what else is out there? Austyn Thurman will go through it with you in plain language. If it's doing what you want, leave it alone.
RMDs and Taxes, With Your CPA
Required minimum distributions (RMDs) are generally taxed as income, and they can raise your income in a year you didn't expect. Austyn Thurman works with your CPA to see how your income sources fit together. Tax advice stays with your CPA.
Educational Workshops and Webinars
Education comes first. You'll learn how income, annuities and life insurance work, what they cost and how to tell what's guaranteed, with no pressure to buy anything.
Three Steps, at Your Own Pace
You Talk, We Listen
Book a call and tell Austyn Thurman what's on your mind: your family, your plans and what you already have. There's no obligation.
You Learn Your Options
Austyn Thurman educates you on what you own and what's available, in plain language, including the risks and the costs.
You Decide
If you want to work with Austyn Thurman, great. If someone else is a better fit, you'll hear that instead. Either way, you can still call with a question later.
We're Not Alone in This
Thurman Financial works alongside two independent companies, so the right expertise is there when your situation calls for it.
Joe Clark
Business Development Advisor, Brokers' Choice of America
Joe Clark is Austyn Thurman's point person at Brokers' Choice of America, with 23 years of working with retirees, pre‑retirees and independent advisors.
James Jurica
CFP® CLU® ChFC® RICP®, Wealth Watch Advisors, Inc.
James Jurica is Austyn Thurman's point person at Wealth Watch Advisors, with a main focus on the investment management side of financial planning.
Advisory services are offered through Wealth Watch, an SEC‑registered investment adviser.
Brokers' Choice of America and Wealth Watch Advisors, Inc. are independent companies, separate from Thurman Financial LLC. Investment advisory services are offered only through Wealth Watch Advisors, Inc.
Common Questions
Education comes first, so here are straight answers to common questions. The full FAQ covers the rest.
I already have an advisor or broker. Can I still talk to you?
Yes. Several people have reached out to me because they've already sat down with a financial planner or a broker and just want to know what else is out there. I'll give you an opinion on a life insurance policy or fixed annuity you own, in plain language. I can't give you an opinion on variable annuities, variable life, stocks, bonds or mutual funds. If what you have is working for you, I'll tell you to leave it be.
Learn about policy reviews →Do I have to buy anything if I call?
No. There's no obligation. Education comes first, and I'm here to give you the information. If you want to work with me, great. If you'd rather take what you learned and go somewhere else, that's fine too. At the end of the day, it's got to be your decision.
What if I decide not to work with you?
That's fine, and you can still call me with a question down the road. I'm here to help you make the right decision for your family, and sometimes that's not me. If I'm not the right person, I want you to know what's out there so you still make the right decision with somebody else. I'm not going anywhere, so you'll know who to call.
Do you manage investments or give investment advice?
No. I'm licensed to sell insurance, and I'm not an investment adviser or a securities broker. I don't manage investment accounts, and I don't tell people which securities to buy or sell. My work is insurance products: life insurance and annuities. Managing a portfolio takes a registered investment professional, and that isn't what I offer.
What is an annuity?
An annuity is a contract you make with an insurance company. You pay in, either a lump sum or over time. The money generally grows tax‑deferred, and the company can turn it into income later, including income for life if you choose that option. Guarantees depend on the financial strength and claims‑paying ability of the company. Most annuities charge you for taking out too much too early, so money you may need soon usually doesn't belong in one.
Learn how annuities work →What is an IUL?
IUL is short for Indexed Universal Life. It's permanent life insurance with a cash value. The insurance company credits interest to that cash value based partly on a market index, such as the S&P 500, up to limits set by the policy. Your money isn't invested in the index. The policy's charges come out every year, whether or not any interest is credited, so a policy that isn't funded properly can shrink or lapse.
Learn how an IUL works →